SHORT VERSION
You can’t get an accurate profit number out of the accounting file at year end, because that file has totals for the company and no way to sort them by job. Profit is per job, and it gets assembled while the job is open. Every hour, every purchase, every pull off truck stock and every return credit has to be charged to a job number on the day it happens. Then the job closes with estimated hours and material compared against what actually got charged, and you have the number that week.
The reason it shows up at tax time is that tax time is the first moment anybody adds it up. If you want to figure out your profitability accurately, the number is per job, and it gets built while the job is still open. Every hour and every purchase has to land on a job number the day it happens. Then you know what a job made the week it closes instead of finding out in March that the year was fine or it wasn’t.
What the accounting file can tell you, and what it can’t
Your P&L tells you what the company took in and what it spent over a period. Both numbers are correct. Neither one is attached to a job.
So at the end of the year you know whether the company made money, and you still don’t know whether the panel changes are carrying the remodels or the remodels are carrying the panel changes. Job costing is the same money, sorted by job instead of by month. The sorting has to happen while the work is happening, because that is the only point at which anybody knows which job the money belongs to.
Where does the cost come off the job?
A journeyman pulls a handful of devices, a couple of breakers and a box of connectors off the truck at ten in the morning and puts them in the wall. Nothing on the work order asks what came off the truck, so that material stays sitting in whatever you bought it under last quarter. It never reaches this job.
Somebody makes a supply house run in the middle of the afternoon. The purchase goes on the company account with no job number on it, because at the counter there’s no field asking for one, and the receipt rides back in the truck. The office ends up building the job’s material cost out of whatever paperwork made it inside the building.
Then half of it goes back the following week. The credit lands on the account and there’s nothing connecting it to the job it was bought for, so that job carries material it never used.
Hours work the same way. If the only place to record time is a timecard due at the end of the week, there is nowhere to put a job number on Tuesday morning. A day that covered two service calls and three hours of punch work on a remodel goes onto the card as one block of hours, because that is the only shape the form has.
Then the homeowner asks for an extra circuit on Thursday and it gets installed. The hours land on the job. The price never does, because nothing between the request and the work turns added scope into a priced line on that job number.
Make the job number the thing every cost has to attach to
The job number has to exist before the work does. Assigned when the call is booked or when the proposal is signed, on the work order, on the phone in the truck, on the purchase order at the counter. Nothing gets clocked, bought, or pulled off a truck without one.
The person who spends it is the person who records it, at the moment it’s spent. That means the entry lives where the spending happens, which is the phone in the truck and the account at the supply house, not a form back at the shop at the end of the week. The office cannot reconstruct this later, and asking it to is where the number goes soft.
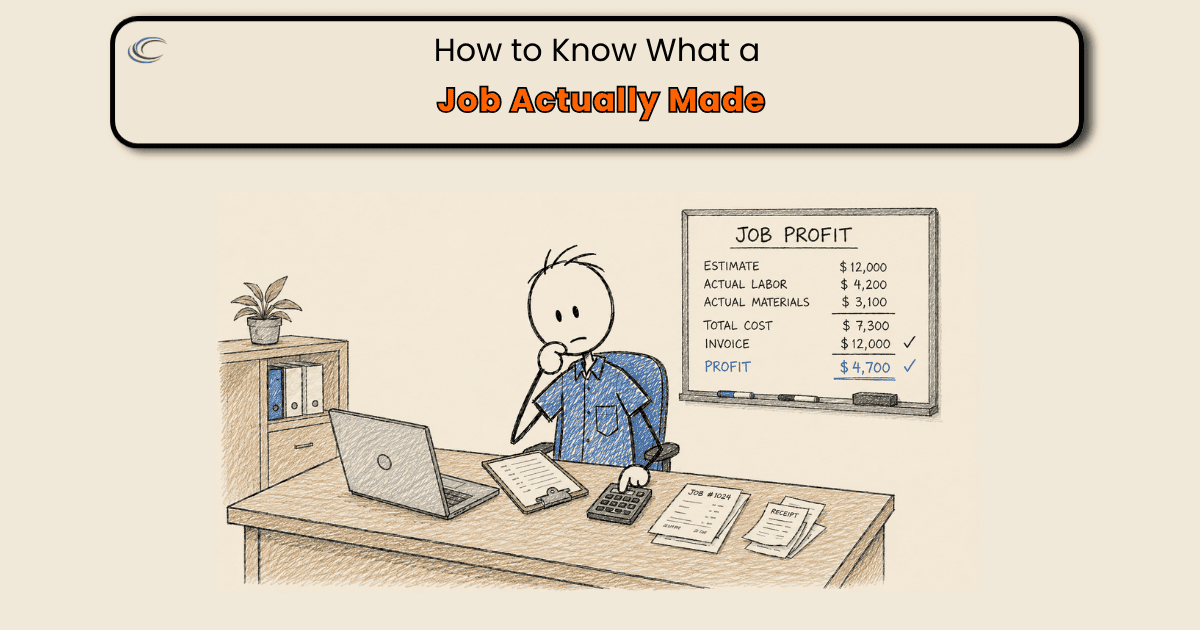
Then put a gate on the back end. A job doesn’t get marked complete until the material used is recorded, the receipts are attached, the returns are credited back to it and the hours are coded. Add one required step to closeout that puts estimated hours and material next to what actually got charged. A job that can’t close until those fields are filled is a job that has a real number the day it closes.
When the number shows up
Once cost is landing on jobs while they’re open, the useful moment is the week a job closes. You can see which jobs ran past their estimated hours while you still remember why.
After a few months of it you have something better than a per-job number. You have a per-type number: what a panel change really runs against what you’re charging for it, which remodels eat their labor budget, whether the tenant improvement work is worth the trips it takes. Knowing what each kind of work actually costs you is what changes what you bid and what you stop taking.
Common questions
Do I need different software to do job costing?
Not necessarily. Three things have to exist somewhere: a job number that gets created before the work starts, a way to attach hours and purchases to it from the field, and a way for both to reach whoever does your books. Check what you already own against those three before you buy anything, because whichever one is missing is the thing you’re actually shopping for.
How do I handle truck stock without counting every wire nut?
Record what has real money in it: devices, breakers, cable, fittings by the box, anything you’d notice if it went missing. The entry has to be part of completing the job, not a separate inventory chore that happens later. Truck stock that gets installed and never recorded is material you already paid for and never charged anybody for.
Should service calls get job costed, or just the bigger projects?
Both. Projects get the attention because the dollars are visible, but service work is where the small leaks live: the supply house trip on a one hour call, the truck stock nobody logged, the drive time that never got coded. A service call takes about thirty seconds to cost if the job number is already on the work order.
What do I do about the jobs that are already open?
Pick a start date instead of trying to rebuild history. Jobs already running get closed the way they were started. Everything opened after that date gets a job number and the closeout step, and you’ll have real numbers on new work within a few weeks.